Navy Federal Credit Union

Screenshots
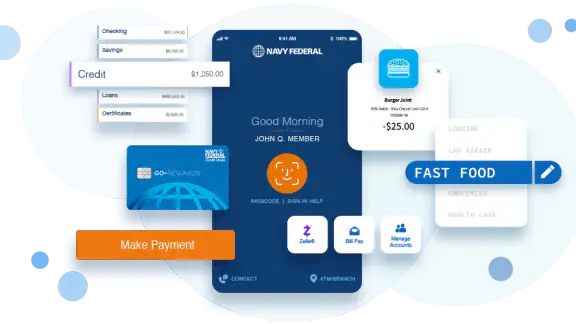
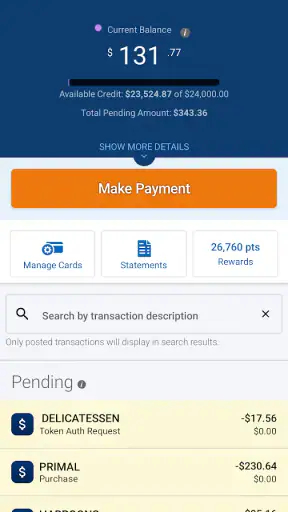
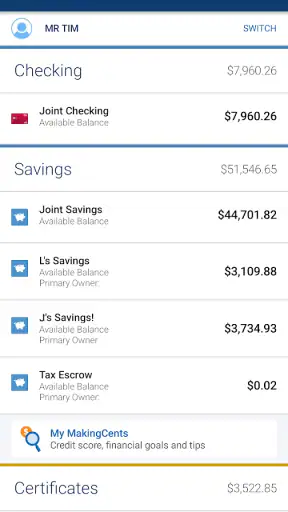
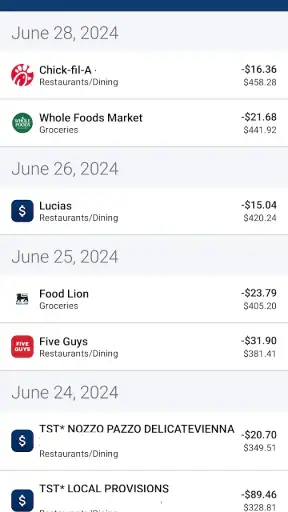
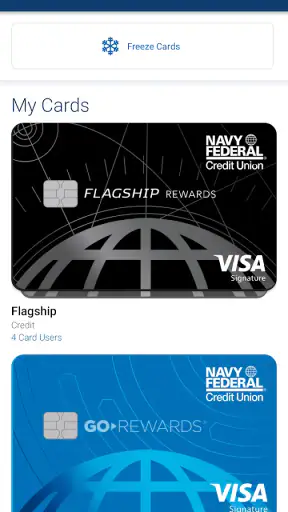
Details
- Rating
- 43.19K reviews
- Version
- 2026.8.1
- Developer
- Navy Federal
Analysis by Norviv
I approach any mobile banking app with a little more caution than a typical shopping or entertainment download. It is handling money, account details, and decisions that can affect my everyday life, so convenience is only half the test. Navy Federal Credit Union is the finance app from Navy Federal, and after spending time with it, I see a practical member-banking tool rather than a flashy all-purpose money manager. Its purpose is straightforward: give Navy Federal members a mobile way to stay connected with their credit union.
The app is free, carries an Everyone age rating, and has been available since July 29, 2011. That long presence matters to me because it suggests this is an established part of the credit union’s digital service rather than a short-lived experiment. Its current version is 2026.8.1 and it requires Android 11 or later. On the wider Android store, it has passed ten million installs, with a 3.7 average from roughly one hundred ten thousand ratings and about forty-three thousand written reviews. Those figures point to a large, active audience, but they also tell me not to confuse popularity with a universally smooth experience.
Trust starts with knowing what the app is—and what it is not
The first question I would ask a friend is whether they already use Navy Federal. This is not a neutral budgeting app that makes sense for everyone with a bank account. It is built around Navy Federal Credit Union, so its value depends heavily on having a relationship with that institution. If you are already a member, the app can put routine account management closer at hand. If you are comparing banks and credit unions, the app alone should not decide where you keep your money.
That distinction is important for trust. A familiar interface can make financial activity feel simple, but the app remains one part of a larger banking relationship. I would still think about the credit union’s account terms, support options, eligibility requirements, and the way I prefer to handle sensitive issues. The mobile application can reduce friction for daily tasks; it does not replace careful decisions about the underlying financial service.
The developer shown for the app is Navy Federal, which gives the product a clear connection to the institution it represents. I prefer that kind of direct identity in a finance app. It makes me less likely to wonder whether I am dealing with an unrelated third-party utility using a similar name. Even so, I would install it through the official app store and check the developer name before signing in, especially if I were searching from a new phone.
The store summary, “Our Members Are the Mission,” is a short statement rather than a detailed explanation of how the app works. I would not treat that phrase as evidence of security, privacy, or customer service quality. Trust has to come from the choices visible while using the app: whether sign-in is clear, whether account actions are understandable, and whether the app gives me enough control to pause before something consequential happens.
Routine banking is where the app earns its place
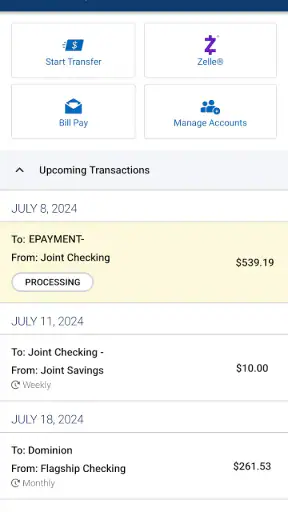
In my experience, the strongest reason to keep a credit union app installed is not novelty. It is the ability to check what is happening without waiting for a desktop session or a branch visit. A quick balance check can answer whether a bill is safe to pay. Looking over recent activity can help me notice an unfamiliar charge while the details are still fresh. These small moments add up, particularly for someone who wants regular awareness without building an elaborate spreadsheet.
Stories Picked for You
Life360 Works Better When Your Household Agrees on What to Share
YouVersion Bible Fits Scripture into Everyday Phone Routines
Matchington Mansion Review: Match-Three Puzzles With a Place to Restore
Android Auto Shows Why Safer Driving Software Does Less
Google Find Hub Runs on Shared Devices and Quiet Trust
Sygic GPS Navigation: The Ultimate Offline Travel Companion
I find this kind of access most useful when I treat it as a checking habit rather than an emergency tool. For example, imagine I am leaving work and need to pay for groceries, fuel, and a prescription before the weekend. I can review the account first, compare the available money with pending obligations, and avoid relying on a rough memory of my balance. That does not make the decision risk-free, but it gives me better information at the moment I need it.
A second useful routine is reviewing activity after a busy day. Instead of waiting until the end of the month, I can look for transactions that do not fit my own behavior. The important insight here is that mobile banking is often more valuable for early awareness than for dramatic problem-solving. If something looks wrong, seeing it promptly gives me more time to contact the institution and document what happened.
That said, I would not use this app as my only financial planning system. A banking app can show account information and support account-related actions, but it may not provide the same broad household view as a dedicated budgeting service. Someone managing several institutions, shared expenses, investments, and long-term goals may prefer a separate planner. The trade-off is simple: Navy Federal’s app is more directly tied to the credit union relationship, while a specialized finance tool may offer a wider cross-account picture.
Controls matter more than a polished first impression
When I review a finance app, I pay attention to moments where the user can stop, verify, or change course. Signing in is one of them. I want to know which account I am entering, whether the screen makes the next action obvious, and whether a sensitive request is presented in plain language. I also avoid rushing through prompts just because I have used the app before. A familiar device can encourage careless tapping, and financial mistakes are harder to undo than an accidental social-media post.
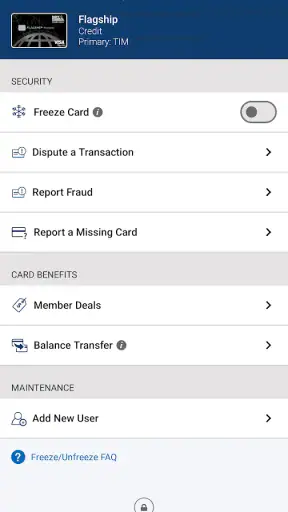
Account controls are another area where I look for agency. The useful question is not simply whether an app has many functions. It is whether I can understand what an action will do before confirming it. Moving money, changing account settings, or responding to a security prompt should feel deliberate. If a screen is crowded or a label is vague, I would pause and use the institution’s support channel rather than guess.
One practical habit is to separate observation from action. I first open the app to review balances and activity, then close it if I only needed information. When I need to make a change, I return with that single purpose in mind. This reduces the chance of making an unnecessary transfer or approving something while distracted. It is a simple workflow, but it is particularly helpful on a small phone screen.
I also recommend checking the app after an update instead of assuming every control is in the same place. The current version is 2026.8.1, and mobile interfaces can change as applications are maintained. A changed menu is not automatically a problem, but it is a reason to slow down before performing a high-impact action. I would rather spend an extra minute reading than treat a banking screen like a familiar calculator.
Privacy decisions deserve attention at the sensitive moments
Financial apps naturally bring data-sensitive moments. The most obvious is sign-in, but it is not the only one. A user may encounter device prompts, security checks, notifications, or requests connected with account activity. I do not grant access automatically. I read what the prompt is asking, decide whether it is necessary for the task, and consider whether I want that channel active on my particular phone.
This is where I think user choice is more meaningful than broad claims about safety. I cannot judge an app’s data practices from its name, its install count, or a reassuring slogan. I look for clear explanations and settings that let me make an informed decision. If a permission appears unrelated to what I am doing, I stop and investigate through official support rather than accepting it merely to get past a screen.
Notifications deserve the same care. They can be useful for keeping an eye on account activity, but a lock-screen message may reveal more than I want visible to someone nearby. I would review the phone’s notification settings and choose a level of detail that fits my environment. Someone living alone may accept more detail than someone who shares a workspace or regularly lends their phone to family members.
Device context also changes the risk. I would avoid signing in on a borrowed phone, a public device, or a handset that I do not control. On my own phone, I would keep the operating system supported and use a screen lock. Since the app requires Android 11 or later, compatibility is not just a technical footnote: it also means an older device may need attention before installation, and someone using outdated hardware should consider whether the device itself is still appropriate for financial access.
For iPhone users, the decision process is similar even though the operating-system requirement mentioned here is for Android. I would still verify the official developer identity in the relevant store, review the app’s privacy information there, and avoid relying on a search result that looks familiar. The principle is the same: confirm who published the app and make choices based on visible information, not assumptions.
Where the experience can become frustrating
The 3.7 average tells me that the app works well enough for many people but does not deliver a frictionless experience to everyone. A rating is not a diagnosis, so I would not claim that every lower review reflects the same problem. Still, the middling score is useful context for setting expectations. Mobile banking depends on more than the app itself: device compatibility, connectivity, authentication, account status, and backend availability can all affect a session.
That dependency is the main limitation I feel with this type of product. If I need immediate access during weak reception, after changing phones, or while a security check is required, convenience can disappear quickly. A banking app is helpful when the surrounding conditions cooperate. It is not a substitute for knowing how to contact Navy Federal through another official channel when the mobile route is unavailable.
I also would not choose it if my main goal were detailed financial analysis. Someone who wants one dashboard for multiple banks, automatic categorization across every account, or extensive planning tools may be better served by a dedicated budgeting application. That choice introduces its own privacy and account-linking considerations, so “more features” does not automatically mean “better.” It simply reflects a different priority.
Likewise, a person who rarely uses mobile banking may prefer a browser or direct support. Installing an app only to perform one occasional task can create another place to manage sign-in details and notifications. Navy Federal’s app makes the most sense for members who genuinely want regular mobile access, not for someone who feels obligated to use an app because it exists.
Small workflows that make a real difference
My first recommendation is to use a two-pass check for important actions. On the first pass, I read the account information and confirm the amount or destination. On the second, I review the confirmation screen before submitting. This is especially useful when I am tired, multitasking, or using a small display. The extra pause protects against ordinary human errors such as selecting the wrong account or misreading a decimal point.
My second recommendation is to keep a simple record of unusual activity outside the app. If I see a transaction I do not recognize, I note the date, amount, and merchant description before contacting support. That record helps me explain the issue clearly and prevents me from repeatedly reopening the app while trying to remember what I saw. It is not a special feature; it is a better workflow built around the information the app presents.
A third insight is to review privacy choices when circumstances change. Moving from a private home to a shared office, replacing a phone, or adding a family member to the device can change what notifications and saved sign-in conveniences are appropriate. I would not set these choices once and forget them. The right balance between speed and discretion depends on how the phone is actually used.
Finally, I would keep the app’s role narrow in my head. It is a way to interact with Navy Federal from a mobile device, not proof that every financial decision is sensible. I still compare bills with my broader budget, question unfamiliar activity, and avoid making rushed choices just because the account screen is easy to open.
Who should install it and who should look elsewhere
I would recommend Navy Federal Credit Union to an existing Navy Federal member who wants convenient access to everyday account information and prefers handling routine banking from a phone. It is also a reasonable fit for someone who checks activity regularly and is willing to pay attention to sign-in, notification, and confirmation choices. The free price removes one obvious barrier, although the value still depends on already having a reason to use Navy Federal’s services.
I would be more cautious about recommending it to someone choosing a financial institution from scratch. The app cannot answer whether Navy Federal is the right credit union for that person, and a good mobile experience should not outweigh account terms or service needs. I would also point frequent travelers toward a backup plan for times when the phone, connection, or authentication process is not cooperating.
People who want a complete financial command center may find a broader budgeting product more suitable. People who prioritize direct control over one credit union relationship may prefer this focused approach. Neither preference is universally correct. The important trade-off is between institution-specific access and cross-provider financial visibility.
My cautious verdict
Navy Federal Credit Union is a useful, established finance app when its purpose matches your situation: you are a Navy Federal member and want mobile access to your credit union relationship. I like the practical value of checking account activity in ordinary moments, and I appreciate that the app’s identity is clearly tied to Navy Federal rather than presented as a generic money tool.
My recommendation comes with a deliberate condition: use it thoughtfully. Read prompts, review sensitive actions before confirming them, manage notification visibility, and keep another official support route in mind. The app can make banking more convenient, but convenience should not turn into automatic approval of every request or careless handling of private information.
With that mindset, I see it as a solid choice for routine Navy Federal access, not as a replacement for financial planning or careful account judgment. If you value direct mobile control over your Navy Federal accounts and are comfortable making your own privacy choices, it is worth trying; if you need multi-bank analysis or dislike app-based account management, a different approach will suit you better.
Frequently Asked Questions
01What is Navy Federal Credit Union, and who can join?
Navy Federal Credit Union is a member-owned financial institution offering checking and savings accounts, credit cards, loans, mortgages, and other banking services. Membership is generally available to active-duty and retired members of the U.S. armed forces, veterans, Department of Defense personnel, certain government employees, and eligible family members. Before downloading the app, confirm that you qualify for membership and have the required identification or account information.
02What can I do with the Navy Federal mobile app?
The Navy Federal mobile app lets members manage many everyday banking tasks from an Android or iOS device. Depending on account eligibility and app availability, you can review balances and transactions, transfer money, pay bills, deposit checks using mobile capture, manage cards, locate branches or ATMs, and receive account alerts. Some services may require additional verification, enrollment, or specific account permissions.
03Is the Navy Federal app safe to use for mobile banking?
The app is designed with security features intended to protect account access and financial information, including login authentication, device security controls, alerts, and safeguards for mobile check deposits and transfers. However, no banking app eliminates every risk. Download it only from the official Apple App Store or Google Play Store, keep your operating system updated, avoid public Wi-Fi for sensitive activity, and never share passwords or verification codes.
04Are there fees for using the Navy Federal mobile app?
Navy Federal generally does not charge a separate fee simply for downloading or using its official mobile banking app, but normal account terms and service charges may still apply. For example, fees could depend on the transaction, account type, overdraft activity, wire service, ATM usage, or mobile carrier data plan. Review the current fee schedule and your wireless provider’s terms before relying on mobile features.
05What should I do if I cannot log in or the app is not working?
If the app will not open, freezes, or rejects your login, first check your internet connection and confirm that you are using the latest version from the official app store. Restarting the device or reinstalling the app may help, although you should know your login details before doing so. For locked accounts, forgotten credentials, suspicious activity, or persistent technical problems, contact Navy Federal through an official support channel rather than a link in an unexpected message.


